Navigating Inflation 2026: Protect Your Purchasing Power by 8%
Anúncios
Navigating Inflation in 2026: 3 Personal Finance Strategies to Protect Your Purchasing Power by 8%
As we look ahead to 2026, the specter of inflation continues to loom large over personal finances. The erosion of purchasing power is a silent thief, steadily diminishing the value of your hard-earned money. For many, the goal isn’t just to maintain their current financial standing but to actively protect purchasing power, aiming for a significant safeguard against inflationary pressures. This article will delve into three crucial personal finance strategies designed to help you shield your wealth and potentially protect your purchasing power by a substantial 8% in the coming year. Understanding these strategies and implementing them diligently can make a profound difference in your financial well-being.
Anúncios
The Persistent Threat of Inflation: Why 2026 Demands Proactive Measures
Inflation is not a new phenomenon, but its recent persistence and volatility have brought it to the forefront of global economic concerns. While central banks and governments employ various tools to manage it, individuals must take proactive steps to mitigate its impact on their personal finances. In 2026, experts anticipate continued inflationary pressures, driven by a complex interplay of supply chain issues, geopolitical events, labor market dynamics, and shifts in consumer demand. Without a robust strategy, your savings, investments, and even your daily budget could be significantly undermined. The objective here is not merely to survive inflation but to thrive despite it, by consciously working to protect purchasing power.
Consider a scenario where inflation runs at 4% annually. Over a decade, your money loses approximately 30% of its value. This means that an item costing $100 today would cost roughly $148 in ten years. For those living on fixed incomes or with substantial savings, this erosion can be particularly devastating. Even for those with rising incomes, if wage growth doesn’t outpace inflation, real income declines. This makes understanding and combating inflation an imperative for everyone, from young professionals just starting their financial journey to retirees managing their nest eggs.
The 8% target for protecting purchasing power isn’t arbitrary. It represents a significant buffer against typical inflationary environments, providing a tangible goal for your financial planning. Achieving this requires a multi-faceted approach, combining smart investment choices, diligent budgeting, and strategic debt management. Let’s explore how you can build this resilience into your financial framework.
Anúncios
Strategy 1: Smart Asset Allocation and Inflation-Resistant Investments
One of the most effective ways to protect purchasing power is through strategic investment in assets that historically perform well during inflationary periods. Simply holding cash or low-interest savings accounts is a guaranteed way to lose value. The key is to diversify your portfolio with assets that either appreciate with inflation or provide income streams that adjust to rising costs.
Real Assets: Tangible Protection
Real assets are physical assets that tend to retain or increase their value when inflation rises. These include:
- Real Estate: Investment properties, whether residential or commercial, can be excellent inflation hedges. Rental income often increases with inflation, and property values tend to appreciate over time. However, it’s crucial to consider location, market conditions, and property management expenses. REITs (Real Estate Investment Trusts) offer a more liquid way to invest in real estate without direct ownership.
- Commodities: Gold, silver, oil, and other raw materials often see their prices rise during inflationary times. Gold, in particular, is traditionally seen as a safe haven asset. While direct investment in commodities can be volatile, commodity-focused ETFs or mutual funds can provide exposure.
- Infrastructure: Investments in infrastructure projects (e.g., utilities, transportation) can also be inflation-resistant, as their revenues are often tied to long-term contracts that include inflation adjustments.
Inflation-Indexed Securities: Direct Link to Inflation
Certain financial instruments are specifically designed to protect against inflation:
- Treasury Inflation-Protected Securities (TIPS): These U.S. Treasury bonds have their principal adjusted based on changes in the Consumer Price Index (CPI). When inflation rises, the principal value of TIPS increases, and so do the interest payments. This provides a direct hedge against inflation.
- I Bonds (Series I Savings Bonds): Another U.S. Treasury product, I Bonds offer a composite interest rate that combines a fixed rate with an inflation rate. This makes them attractive for protecting smaller savings amounts, especially for individuals.
Equities: Companies with Pricing Power
Not all stocks are created equal when it comes to inflation. Focus on companies that possess strong ‘pricing power’ – the ability to raise prices without significantly impacting demand. These often include:
- Companies with Strong Brands: Established brands with loyal customer bases can often pass on increased costs to consumers.
- Companies in Essential Sectors: Utilities, healthcare, and certain consumer staples industries often have stable demand regardless of economic conditions.
- Companies with Low Debt and High Margins: These businesses are better positioned to absorb rising input costs without severely impacting profitability.
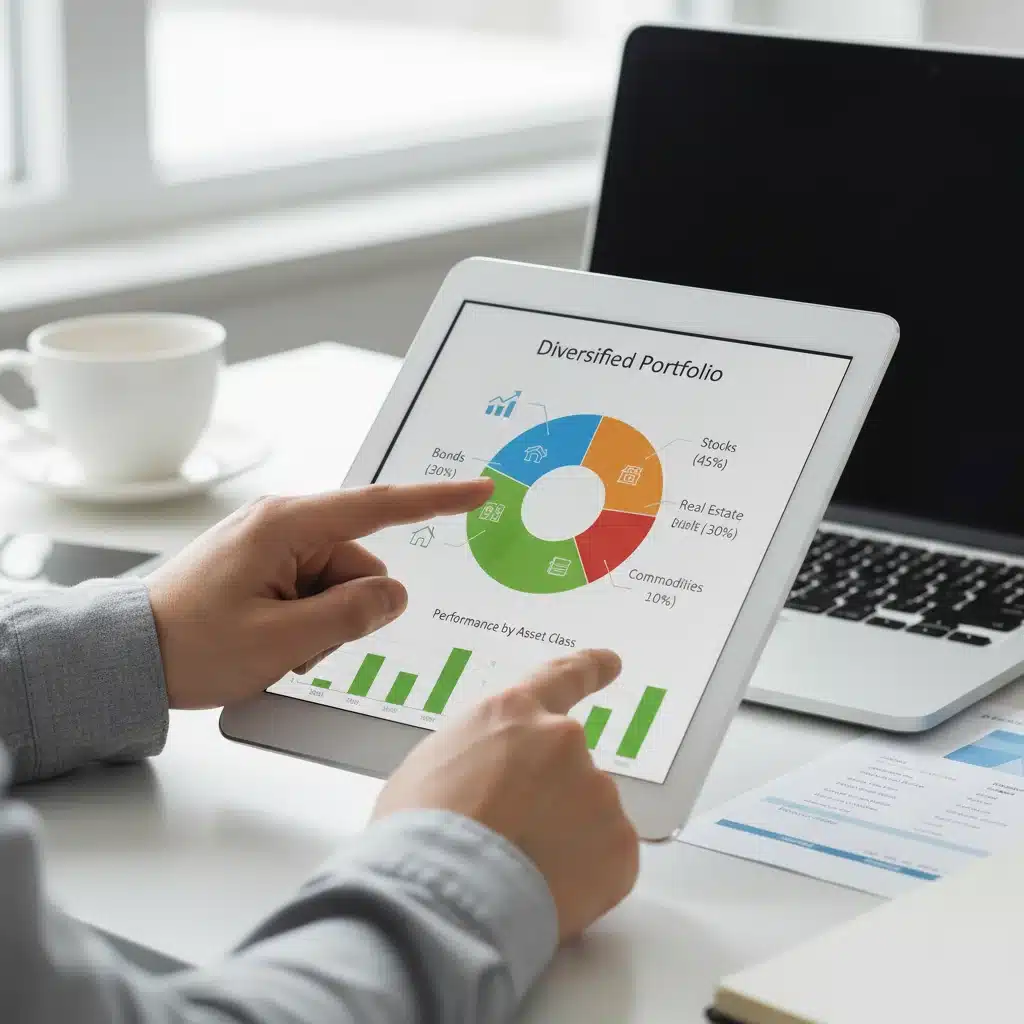
Diversification is paramount. A well-balanced portfolio that includes a mix of these inflation-resistant assets, tailored to your risk tolerance and financial goals, is key to effectively working to protect purchasing power.
Strategy 2: Aggressive Debt Management and Optimized Cash Flow
While inflation can erode the value of debt (making it theoretically easier to pay back with devalued dollars), high-interest debt can quickly become a significant burden, especially if your income doesn’t keep pace. Therefore, aggressive debt management and optimizing your cash flow are critical components of any strategy to protect purchasing power.
Prioritize High-Interest Debt Repayment
The interest rates on credit cards, personal loans, and other variable-rate debts can skyrocket during inflationary periods as central banks raise rates to combat inflation. This makes paying down these debts a top priority. Every dollar you spend on high-interest debt is a dollar that isn’t working for you or being invested. Consider strategies like the debt snowball or debt avalanche methods to systematically eliminate these liabilities. Reducing your debt burden frees up cash flow that can then be used for investments or to build a stronger emergency fund.
Refinance When Possible
If you have fixed-rate debt, such as a mortgage, and interest rates are still relatively low, consider refinancing to secure an even lower rate or to shorten the loan term. This can lock in lower payments, freeing up cash. However, be cautious with variable-rate debt in a rising interest rate environment, as refinancing to a variable rate could expose you to greater risk.
Optimize Your Budget and Control Expenses
Inflation directly impacts the cost of living. To counteract this, a meticulous review of your budget is essential. Identify areas where you can cut back or optimize spending without significantly impacting your quality of life. This might include:
- Subscription Services: Review and cancel unused subscriptions.
- Utilities: Implement energy-saving measures at home.
- Groceries: Plan meals, buy in bulk when appropriate, and avoid impulse purchases.
- Transportation: Consider carpooling, public transport, or optimizing fuel efficiency.
- Discretionary Spending: Evaluate entertainment, dining out, and luxury purchases.
The goal is not just to cut expenses but to understand where your money is going and ensure it aligns with your priorities. Every dollar saved is a dollar that retains its value more effectively, helping you to protect purchasing power.
Increase Income Streams
While managing expenses is crucial, increasing your income is an equally powerful way to combat inflation. This could involve:
- Negotiating Salary Increases: Regularly assess your market value and negotiate for raises that at least keep pace with inflation.
- Developing New Skills: Acquire in-demand skills that can lead to higher-paying job opportunities or career advancement.
- Side Hustles: Explore freelance work, consulting, or starting a small business to generate additional income.
- Passive Income: Invest in dividend stocks, rental properties, or other assets that generate passive income streams.
By actively managing debt and optimizing cash flow, you create a stronger financial foundation, allowing you to absorb inflationary shocks and allocate more resources towards growth and protection.
Strategy 3: Human Capital Investment and Adaptive Financial Planning
Your greatest asset is often yourself – your skills, knowledge, and ability to earn. Investing in your human capital and adopting an adaptive approach to financial planning are paramount to effectively protect purchasing power in a dynamic economic environment.
Continuous Learning and Skill Development
In an inflationary environment, the demand for highly skilled labor often remains strong, allowing individuals with specialized expertise to command higher wages. Continuously investing in your education, acquiring new certifications, or learning new technologies can significantly enhance your earning potential. This not only helps you keep pace with rising costs but can also provide a competitive edge in the job market. Think of it as an investment in your personal ‘inflation hedge’ – your ability to generate income that outpaces the cost of living.
- Formal Education: Pursuing higher degrees or specialized certifications.
- Online Courses and Workshops: Leveraging platforms like Coursera, edX, or LinkedIn Learning.
- Networking: Building connections that can open doors to new opportunities.
- Mentorship: Learning from experienced professionals in your field.
The goal is to ensure your skills remain relevant and valuable, allowing you to negotiate for better compensation and maintain a strong income trajectory. This direct impact on your income is one of the most powerful ways to protect purchasing power.
Adaptive and Flexible Financial Planning
Traditional financial plans often assume relatively stable economic conditions. However, in an era of persistent inflation, your financial plan needs to be dynamic and adaptable. Regularly review and adjust your budget, investment strategy, and financial goals based on prevailing economic conditions and inflation rates.
- Regular Financial Reviews: At least annually, revisit your entire financial plan. Are your investments still aligned with your goals and risk tolerance in an inflationary environment?
- Emergency Fund Adjustment: Ensure your emergency fund accounts for rising costs. If your monthly expenses have increased due to inflation, your emergency fund should grow proportionally.
- Retirement Planning Adjustments: Inflation can significantly impact the amount you’ll need in retirement. Re-evaluate your retirement savings goals and contribution rates to account for a higher cost of living in the future.
- Professional Guidance: Consider working with a financial advisor who specializes in inflation-hedging strategies. They can provide personalized advice and help you navigate complex market conditions.
Being flexible means not being rigid in your approach. If certain investments aren’t performing as expected due to inflation, be prepared to reallocate. If your income opportunities shift, adjust your saving and spending habits accordingly. This proactive and responsive approach ensures that your financial plan remains robust and effective in its mission to protect purchasing power.
The Cumulative Impact: Achieving an 8% Shield for Your Purchasing Power
Individually, each of these strategies offers a layer of protection against inflation. However, their true power lies in their cumulative effect. By combining smart asset allocation, aggressive debt management, optimized cash flow, and continuous investment in your human capital, you create a formidable defense against the erosion of your wealth. Aiming to protect purchasing power by 8% is an ambitious yet achievable goal when these strategies are implemented consistently.
Putting It All Together: A Holistic Approach
Imagine this integrated approach:
- You’ve diversified your investment portfolio to include TIPS, real estate, and companies with strong pricing power. This helps your assets grow at or above the inflation rate.
- You’ve systematically paid down high-interest debt, freeing up significant monthly cash flow. This cash is now available for further investment or to strengthen your emergency fund.
- You’ve optimized your budget, identifying areas of unnecessary spending and reallocating those funds to savings and investments.
- You’ve invested in a new certification that boosts your earning potential by 5-10% annually, ensuring your income growth outpaces inflation.
- You regularly review your financial plan, adjusting your emergency fund and retirement contributions to reflect current economic realities.
This holistic approach doesn’t just react to inflation; it proactively builds resilience. The 8% target isn’t just about outperforming inflation by a small margin; it’s about building a substantial buffer that ensures your financial goals remain within reach, even in challenging economic times. It provides peace of mind, knowing that your financial future is more secure.
Beyond 2026: A Long-Term Perspective on Protecting Purchasing Power
While our focus has been on 2026, the principles discussed here are evergreen. Inflation is a recurring economic cycle, and building habits that consistently aim to protect purchasing power is a lifelong endeavor. The financial landscape is constantly evolving, and staying informed, adaptable, and proactive will always be your best defense.
It’s also important to consider the psychological impact of inflation. Constant worry about rising costs can be stressful. By taking control and implementing these strategies, you empower yourself, transforming anxiety into actionable plans. This proactive stance not only benefits your bank account but also contributes to your overall well-being.
Final Thoughts and Actionable Steps
To summarize, here are the immediate actionable steps you can take to begin protecting your purchasing power:
- Assess Your Current Portfolio: Evaluate your investments for inflation resistance. Consider adding TIPS, real estate, or commodity exposure.
- Audit Your Debts: Identify and prioritize high-interest debts for aggressive repayment.
- Review and Optimize Your Budget: Find areas to cut unnecessary expenses and reallocate funds.
- Invest in Yourself: Identify skills that can increase your earning potential and pursue relevant education or training.
- Schedule Regular Reviews: Make financial check-ups a routine part of your life, adapting your plan as economic conditions change.
By diligently applying these three personal finance strategies, you can confidently navigate the inflationary environment of 2026 and beyond, ensuring that your money continues to work for you and that you effectively protect purchasing power for years to come. Your financial future is in your hands; empower yourself with knowledge and action.