High-Yield Savings Accounts 2026: Are They Still Worth It? Top 5 Options with 4.5%+ APY
Anúncios
Is a High-Yield Savings Account Still Worth It in 2026? Comparing Top 5 Options with 4.5% APY or More
Anúncios
The Evolving Landscape of Savings: What to Expect in 2026
As we step into 2026, the financial world continues its relentless evolution, presenting both challenges and opportunities for savers. For years, high-yield savings accounts (HYSAs) have been a cornerstone for individuals looking to grow their emergency funds and short-term savings beyond what traditional brick-and-mortar banks offer. But with economic shifts, fluctuating interest rates, and the persistent specter of inflation, a critical question emerges: is a high-yield savings 2026 strategy still a wise financial move? This comprehensive guide delves into the current state of HYSAs, analyzes their potential benefits and drawbacks in the coming year, and provides a detailed comparison of the top 5 options offering a compelling 4.5% APY or more.
The allure of a high-yield savings account lies in its ability to offer significantly higher interest rates compared to conventional savings accounts, often without the volatility associated with investment vehicles like stocks or bonds. This balance of competitive returns and relative safety makes them an attractive option for many. However, the economic climate of 2026, influenced by global events, central bank policies, and technological advancements, demands a fresh evaluation. Understanding these dynamics is crucial for anyone considering where to park their hard-earned money.
Anúncios
Our goal is to equip you with the knowledge needed to make an informed decision. We’ll explore the factors that impact HYSA rates, discuss the pros and cons of these accounts in 2026, and provide actionable insights to help you choose the best account for your financial goals. Whether you’re saving for a down payment, building an emergency fund, or simply seeking a better return on your idle cash, this article will serve as your definitive resource for navigating the high-yield savings 2026 landscape.
What Exactly is a High-Yield Savings Account (HYSA)?
Before we dive into the specifics of 2026, let’s briefly recap what a high-yield savings account is and why it gained such prominence. A high-yield savings account is essentially a savings account that offers an annual percentage yield (APY) significantly higher than the national average for traditional savings accounts. These accounts are typically offered by online-only banks or credit unions, which have lower overhead costs compared to their physical counterparts, allowing them to pass those savings on to customers in the form of better interest rates.
Key characteristics of HYSAs include:
- Higher APY: The primary draw, offering returns that can meaningfully outpace inflation, at least more so than traditional options.
- Liquidity: Funds are generally accessible, though some accounts might have transaction limits. They are much more liquid than CDs or investment accounts.
- FDIC/NCUA Insurance: Most reputable HYSAs are insured by the Federal Deposit Insurance Corporation (FDIC) for banks or the National Credit Union Administration (NCUA) for credit unions, protecting your deposits up to $250,000 per depositor, per institution, in case of bank failure. This makes them a very secure option for savings.
- Online-Centric: The majority operate online, meaning fewer physical branches but often robust digital banking tools and customer service.
- Minimal Fees (Often): Many HYSAs come with no monthly maintenance fees, especially if certain conditions are met (e.g., minimum balance).
The popularity of HYSAs surged during periods of rising interest rates, as banks competed to attract deposits. Understanding these fundamental aspects is crucial when evaluating if a high-yield savings 2026 remains a beneficial component of your financial strategy.
The Economic Forecast for 2026: Impact on High-Yield Savings Rates
Predicting the exact economic climate for 2026 is challenging, but we can analyze trends and expert forecasts to anticipate how they might affect high-yield savings 2026 rates. Several key factors influence APY offerings:
Federal Reserve Policy and the Federal Funds Rate
The Federal Reserve’s monetary policy, particularly changes to the federal funds rate, is the most significant driver of savings account interest rates. When the Fed raises rates to combat inflation, banks typically follow suit, increasing their APYs to attract deposits. Conversely, if the Fed lowers rates to stimulate economic growth, HYSA rates tend to decrease. In 2026, depending on inflation levels and economic growth, the Fed could maintain, raise, or lower rates. A stable or rising rate environment would be favorable for HYSAs, while a significant rate cut could diminish their attractiveness.
Inflation Trends
Inflation erodes the purchasing power of money. While HYSAs offer higher returns, it’s essential to consider whether the APY can outpace or at least keep pace with inflation. If inflation remains stubbornly high in 2026, even a 4.5% APY might offer a real (inflation-adjusted) return that is less impactful. The goal of a high-yield savings 2026 strategy should be to preserve and ideally grow your capital in real terms.
Competition Among Online Banks
The competitive landscape among online banks and fintech companies plays a crucial role. These institutions often vie for market share by offering aggressive APY rates. As more players enter the market and technological advancements make it easier to switch banks, this competition could help keep HYSA rates relatively strong, even if the broader interest rate environment is less favorable.
Economic Growth and Stability
A robust economy generally leads to higher demand for credit, which can indirectly support higher deposit rates as banks seek funding. Conversely, an economic downturn might see banks reducing rates as lending opportunities shrink. The overall stability and growth trajectory of the economy in 2026 will undoubtedly influence the value proposition of a high-yield savings 2026 account.
Considering these factors, while predicting the future is impossible, a conservative outlook suggests that HYSAs will likely continue to offer competitive rates relative to traditional accounts, though the absolute APY might fluctuate. The key will be to remain agile and monitor the market for the best offerings.
Are High-Yield Savings Accounts Still Worth It in 2026? The Pros and Cons
With the economic factors in mind, let’s weigh the advantages and disadvantages of holding a high-yield savings 2026 account.
Pros of HYSAs in 2026:
- Superior Returns Compared to Traditional Savings: Even if overall interest rates dip slightly, HYSAs are almost guaranteed to offer a significantly better return than the meager rates of large brick-and-mortar banks. This makes them ideal for emergency funds and short-term savings goals where capital preservation is paramount.
- Safety and Security: With FDIC or NCUA insurance, your deposits are protected up to $250,000. This provides peace of mind, especially during uncertain economic times, making them a safer alternative to volatile investments.
- Liquidity and Accessibility: Funds in HYSAs are readily accessible, typically through online transfers, debit cards, or electronic payments. This high liquidity is essential for emergency funds or money you plan to use in the near future.
- Low Barrier to Entry and Fees: Many HYSAs require no minimum deposit to open and have no monthly maintenance fees, making them accessible to a broad range of savers.
- Inflation Hedge (Partial): While not a perfect hedge, a 4.5% APY or more can help mitigate the effects of moderate inflation, preserving more of your purchasing power than a standard savings account.
Cons of HYSAs in 2026:
- Interest Rate Volatility: HYSA rates are variable and can change frequently based on the federal funds rate and market conditions. While they are high now, there’s no guarantee they will stay at 4.5% or above throughout 2026.
- Inflation Risk: If inflation surges significantly above the APY offered, your real return could still be negative, meaning your money loses purchasing power over time.
- Not an Investment Account: HYSAs are for saving, not aggressive growth. They won’t generate the same long-term returns as a diversified investment portfolio, especially during bull markets. For long-term wealth building, other investment vehicles are usually more appropriate.
- Online-Only Experience: While convenient for many, some individuals prefer the option of in-person banking services, which are typically absent with online HYSAs.
- Taxation on Interest: The interest earned from HYSAs is considered taxable income, which can reduce your net returns, especially for those in higher tax brackets.
In conclusion, for specific financial goals like emergency funds, short-term savings, or money you need to keep liquid and safe, a high-yield savings 2026 account remains an excellent choice. However, it’s crucial to understand its limitations and integrate it into a broader financial plan that includes investments for long-term growth.
Key Features to Look For in a High-Yield Savings Account
When comparing HYSAs in 2026, don’t just focus on the APY. Several other features contribute to the overall value and convenience of an account:
- Annual Percentage Yield (APY): This is the headline number, but ensure it’s a consistent rate and not just a promotional offer. Always compare the APY across different institutions.
- FDIC/NCUA Insurance: Non-negotiable. Ensure your deposits are protected up to the federal limit.
- Minimum Balance Requirements: Some accounts require a minimum balance to earn the advertised APY or to avoid fees. Look for accounts with low or no minimums if you don’t have a large sum to deposit initially.
- Fees: Scrutinize the fee schedule. Avoid accounts with monthly maintenance fees, excessive transaction fees, or fees for services like wire transfers if you anticipate needing them.
- Accessibility and Digital Tools: Evaluate the online banking platform and mobile app. Look for features like easy fund transfers, mobile check deposit, bill pay, and robust security measures.
- Customer Service: While online-only, good customer support via phone, chat, or email is essential for when issues arise.
- Linked Accounts: The ability to easily link to external bank accounts for seamless transfers is a significant convenience.
- Withdrawal Limits: Understand any limitations on the number of withdrawals or transfers you can make per month, though federal limits have largely been lifted.
By considering these features alongside the APY, you can find a high-yield savings 2026 account that perfectly aligns with your financial habits and needs.
Top 5 High-Yield Savings Account Options for 2026 (4.5% APY or More)
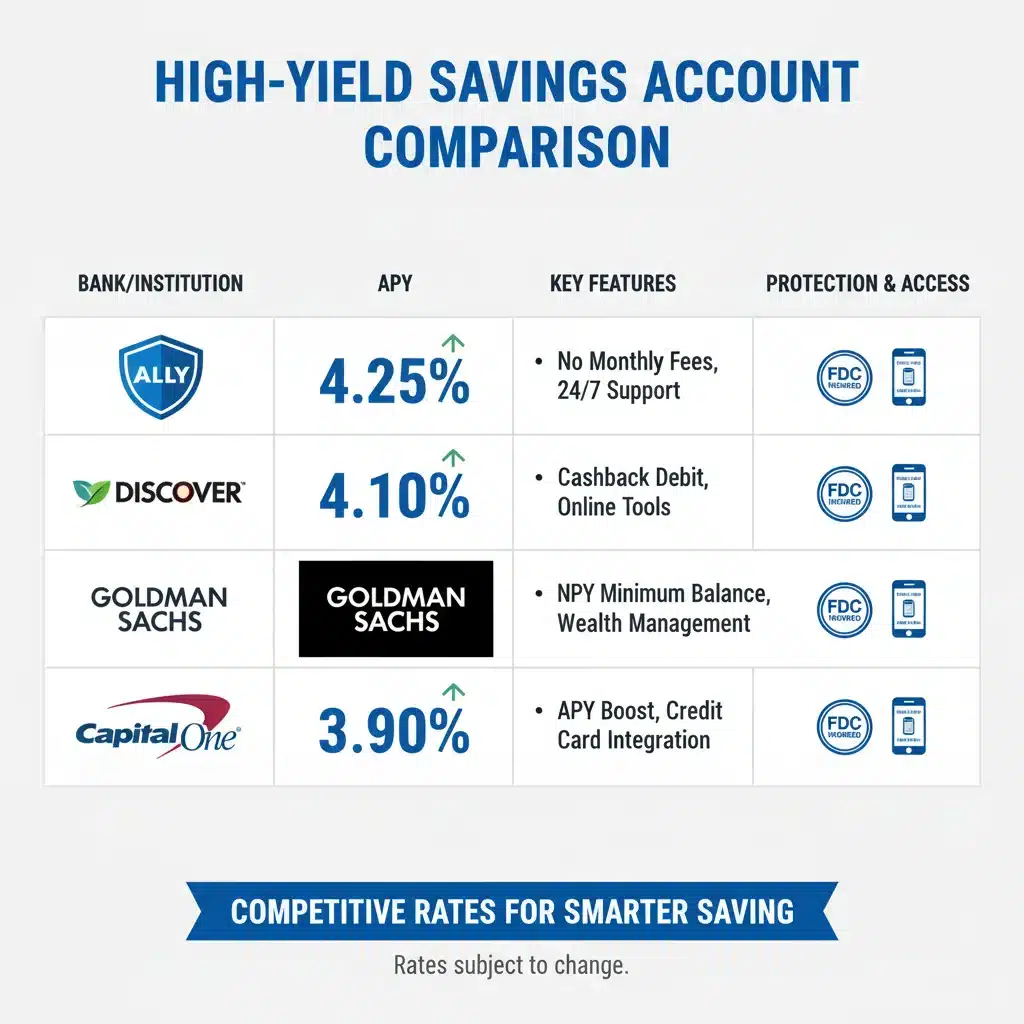
As of late 2025/early 2026, several online banks are consistently offering highly competitive APYs. While rates can fluctuate, these institutions are known for their strong offerings. Here are 5 top contenders, expected to maintain or exceed 4.5% APY, based on current trends and historical performance:
1. Synchrony Bank High-Yield Savings
- Projected APY (2026): Expected to remain competitive, potentially at or above 4.60% APY.
- Key Features: No monthly fees, no minimum balance to open or earn APY. Strong online platform and mobile app. Offers an ATM card for easy cash access (though not for deposits). Excellent customer service reputation.
- Why it Stands Out: Consistent high rates, fee-free structure, and a solid reputation make it a reliable choice for a high-yield savings 2026 account.
2. Marcus by Goldman Sachs Online Savings Account
- Projected APY (2026): Consistently among the top performers, likely around 4.50% – 4.75% APY.
- Key Features: No fees, no minimum deposit to open or maintain. User-friendly online interface and mobile app. Excellent customer support. Offers various tools for financial planning.
- Why it Stands Out: Backed by Goldman Sachs, offering a blend of stability and competitive rates. Known for its simplicity and transparency, making it an attractive high-yield savings 2026 option.
3. Citizens Access Online Savings Account
- Projected APY (2026): Historically competitive, often matching or slightly exceeding market leaders, possibly 4.55% – 4.80% APY.
- Key Features: No monthly maintenance fees. Requires a $5,000 minimum deposit to open, but no minimum to earn the stated APY once opened. Part of Citizens Financial Group.
- Why it Stands Out: A strong option for those with a larger initial deposit, offering consistently high rates without hidden fees. Good for a solid high-yield savings 2026 strategy.
4. Ally Bank Online Savings Account
- Projected APY (2026): A long-standing leader in online banking, expected around 4.40% – 4.65% APY.
- Key Features: No monthly maintenance fees, no minimum deposit. Excellent digital tools, including ‘buckets’ for organizing savings goals. 24/7 customer service. ATM access through Allpoint network.
- Why it Stands Out: Renowned for its comprehensive online banking experience and customer-centric approach, making it a popular choice for a versatile high-yield savings 2026 solution.
5. Capital One 360 Performance Savings
- Projected APY (2026): Expected to maintain a strong position, potentially around 4.35% – 4.50% APY.
- Key Features: No fees, no minimums. Seamless integration with Capital One’s broader suite of financial products (checking, credit cards). Robust mobile app and customer support.
- Why it Stands Out: A great option for those who prefer to keep all their banking with one institution, offering competitive rates and a user-friendly experience for a high-yield savings 2026 account.
Disclaimer: APYs are subject to change and are based on projections for 2026. Always check the latest rates directly with the financial institutions.
Optimizing Your High-Yield Savings Strategy in 2026
Simply opening a high-yield savings 2026 account is the first step. To truly maximize its benefits, consider these strategies:
Automate Your Savings
Set up automatic transfers from your checking account to your HYSA on a regular basis (e.g., weekly, bi-weekly, or monthly). This consistent approach ensures your savings grow steadily without you having to actively think about it. Automation is a powerful tool for building wealth.
Laddering with CDs (for longer-term goals)
While HYSAs are great for liquidity, if you have funds you won’t need for a year or more, consider a Certificate of Deposit (CD) ladder. You can combine a HYSA for your emergency fund with CDs for slightly longer-term goals, potentially locking in even higher rates for a fixed period. This hybrid approach can optimize your overall returns while maintaining some liquidity.
Monitor Rates Regularly
HYSA rates are variable. Make it a habit to check the top rates periodically. If your current bank significantly drops its APY and a competitor offers a much better deal, don’t hesitate to switch. The process of transferring funds between online banks has become increasingly streamlined.
Understand Tax Implications
Interest earned from HYSAs is taxable income. Factor this into your calculations. For very high earners, municipal bonds or tax-advantaged investment accounts might offer better after-tax returns for certain goals, but for readily accessible cash, the HYSA remains a strong contender.
Align with Your Financial Goals
Use your HYSA for specific, short to medium-term goals: your emergency fund (typically 3-6 months of living expenses), a down payment for a house or car, a major vacation, or a large purchase within the next 1-3 years. For longer-term goals like retirement, investment accounts (e.g., 401k, IRA, brokerage accounts) are generally more suitable due to their higher growth potential.
By implementing these strategies, your high-yield savings 2026 account won’t just be a place to store money; it will be an active tool in achieving your financial aspirations.
Beyond HYSAs: Other Savings and Investment Alternatives in 2026
While a high-yield savings 2026 account is an excellent tool, it’s part of a broader financial ecosystem. Depending on your time horizon and risk tolerance, other options might be suitable for different portions of your money:
- Certificates of Deposit (CDs): Offer fixed interest rates for a set term (e.g., 6 months, 1 year, 5 years). They often provide slightly higher rates than HYSAs, especially for longer terms, but your money is locked up until maturity. Good for money you know you won’t need for a specific period.
- Money Market Accounts (MMAs): A hybrid between checking and savings, MMAs offer competitive interest rates (often similar to HYSAs) and sometimes come with check-writing privileges and a debit card. They often require higher minimum balances than HYSAs.
- Treasury Bills (T-Bills): Short-term debt obligations of the U.S. government. They are considered very safe and can offer competitive yields, especially in a rising interest rate environment. You can purchase them directly from TreasuryDirect.
- Short-Term Bond ETFs/Mutual Funds: For those willing to take on a little more risk than a HYSA, but less than stocks, short-term bond funds can offer potentially higher returns. However, their value can fluctuate with interest rate changes.
- Investment Accounts (Brokerage, Roth IRA, 401k): For long-term wealth accumulation (5+ years), investing in a diversified portfolio of stocks, bonds, and other assets through these accounts typically offers the highest potential for growth. These are not alternatives for your emergency fund but are crucial for retirement and other distant goals.
The best approach is often a diversified one, utilizing different financial products for different goals. A high-yield savings 2026 account should be seen as a critical component for liquidity and safety, complementing other investment strategies.
Conclusion: Making the Most of Your Money in 2026 with HYSAs
In conclusion, the question of whether a high-yield savings 2026 account is still worth it can be answered with a resounding yes, especially for specific financial needs. For emergency funds, short-term savings goals, and money that requires both safety and liquidity, HYSAs offering 4.5% APY or more represent an invaluable tool in your financial arsenal.
While the economic landscape will continue to evolve, the core benefits of HYSAs—superior returns over traditional savings, FDIC/NCUA insurance, and easy access to funds—remain highly relevant. By carefully selecting an account based on competitive APY, minimal fees, and user-friendly features, and by integrating it into a holistic financial plan, you can ensure your money works harder for you in 2026.
Stay informed about interest rate trends, be prepared to switch accounts if better opportunities arise, and consistently contribute to your savings. A well-managed high-yield savings 2026 account is not just a place to store money; it’s a strategic decision that empowers your financial security and helps you achieve your short-term aspirations.