The CARES Act and Beyond: 5 Key Financial Literacy Lessons from Recent Economic Stimulus
The economic landscape of the past few years has been nothing short of a rollercoaster, marked by unprecedented challenges and equally unprecedented government interventions. From the initial shockwaves of a global pandemic to the subsequent rollout of massive economic stimulus packages, such as the Coronavirus Aid, Relief, and Economic Security (CARES) Act, individuals and households have been forced to confront their financial realities in new and often uncomfortable ways. While these stimulus measures provided crucial lifelines for millions, they also inadvertently served as a powerful, real-time masterclass in financial literacy. The period offered a unique opportunity to observe, learn, and adapt our personal finance strategies. Understanding the underlying principles and practical implications of these events is paramount for building lasting financial resilience. This article delves into five pivotal financial literacy lessons gleaned from the CARES Act and the broader spectrum of recent economic stimulus efforts, providing actionable insights to empower you for future economic uncertainties.
Anúncios
1. The Indispensable Role of an Emergency Fund: A Core Financial Literacy Lesson
If there’s one overarching lesson that resonated universally from the economic disruptions of recent years, it is the absolute necessity of a robust emergency fund. Before the pandemic, many financial experts preached the importance of having three to six months’ worth of living expenses saved. For some, this advice felt abstract or like a luxury. However, when unemployment spiked, businesses shuttered, and job security became a daily concern for millions, the abstract became terrifyingly real. Those with adequate emergency savings found themselves in a significantly more stable position, able to weather income loss, unexpected medical bills, or other unforeseen expenses without immediately resorting to high-interest debt.
The CARES Act, with its enhanced unemployment benefits and direct stimulus checks, provided a temporary buffer for many. Yet, it also highlighted the precariousness of relying solely on external aid. Government assistance, while vital, can be delayed, insufficient, or temporary. The best defense against personal financial crisis remains a self-funded safety net. This is a foundational financial literacy lesson that cannot be overstated. Building an emergency fund isn’t just about saving money; it’s about buying peace of mind and creating a buffer that allows you to make rational decisions during stressful times, rather than desperate ones.
Anúncios
For those who struggled during the crisis due to a lack of savings, this period served as a harsh but effective wake-up call. It underscored the importance of prioritizing savings, even small amounts, consistently over time. The goal should be to accumulate enough to cover essential expenses for at least three to six months, and ideally even more, especially for those with unstable incomes or dependents. This fund should be easily accessible, typically in a high-yield savings account, but separate from your everyday checking account to avoid accidental spending. The discipline required to build and maintain such a fund is a cornerstone of effective personal finance management and a critical component of strong financial literacy lessons.
2. Understanding and Managing Debt in Times of Uncertainty
The economic stimulus measures also shone a bright light on the pervasive issue of debt and its impact on financial vulnerability. Many individuals and families entered the pandemic carrying significant burdens of credit card debt, student loans, and mortgages. While some provisions of the CARES Act, such as forbearance options for federal student loans and mortgages, offered temporary relief, they also exposed the underlying fragility of debt-heavy financial structures. The temporary pause on payments provided a much-needed reprieve, but it also meant that for many, the debt itself didn’t disappear; it merely accumulated interest or was deferred to a later date.
This experience underscored a crucial financial literacy lesson: proactive debt management is essential, especially when facing economic uncertainty. Understanding the terms of your debt, including interest rates, minimum payments, and potential forbearance options, became critical. Many learned the hard way that ignoring debt only exacerbates the problem. Instead, this period encouraged many to re-evaluate their debt repayment strategies. Some used stimulus checks to pay down high-interest credit card debt, recognizing the long-term benefits of reducing their financial obligations.
The lesson here is twofold: first, strive to minimize high-interest debt as much as possible during stable times, as it becomes a significant liability during downturns. Second, in times of crisis, actively engage with your creditors. Many lenders offered hardship programs, deferrals, or modified payment plans. Those who communicated their financial difficulties often found more favorable outcomes than those who simply stopped paying. This proactive approach to debt, understanding its nuances, and strategically managing it, forms a vital part of comprehensive financial literacy lessons.
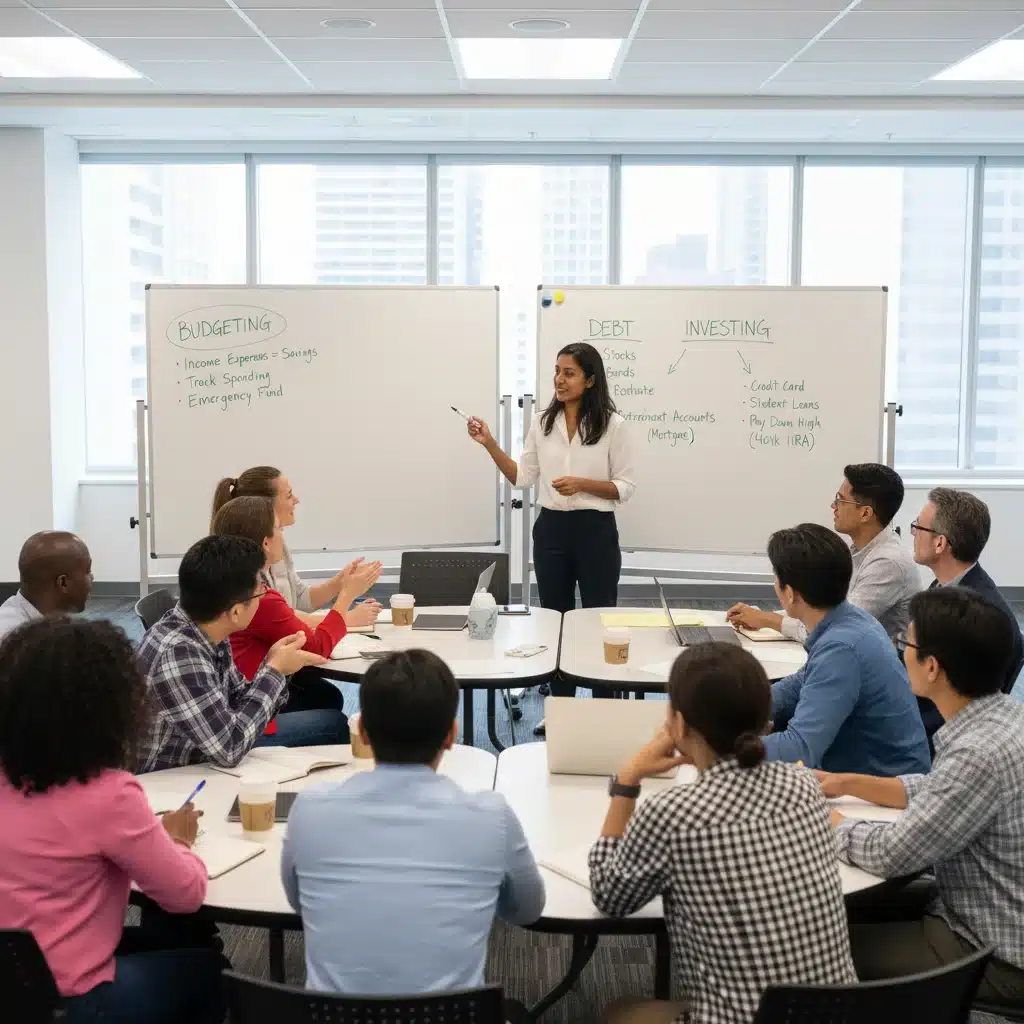
3. The Importance of Budgeting and Tracking Spending
When incomes became unpredictable and expenses shifted dramatically (e.g., less commuting, more grocery spending), the discipline of budgeting moved from being a good idea to an absolute necessity. For many, the stimulus checks and enhanced unemployment benefits were the first time they had a clear influx of funds that wasn’t immediately earmarked for existing bills. This forced a conscious decision-making process: how would these funds be used?
This period served as a powerful practical application of fundamental budgeting principles. Individuals had to prioritize essential needs, distinguish between wants and needs, and allocate funds strategically. Those who already had a budget in place found it easier to adjust to new financial realities, simply modifying their existing framework. For others, the crisis was the catalyst to finally create one. Tracking spending became crucial not just for managing current funds but also for projecting future needs and identifying areas for potential savings.
A key financial literacy lesson here is that budgeting isn’t about restriction; it’s about control and awareness. It provides a clear picture of where your money is going, allowing you to make informed decisions about your financial priorities. Whether using a spreadsheet, a budgeting app, or simply pen and paper, the act of regularly reviewing income and expenses empowers individuals to take charge of their financial lives. This heightened awareness is invaluable for both short-term crisis management and long-term financial goal achievement, solidifying its place among essential financial literacy lessons.
4. Diversifying Income Streams and Skill Sets: Building Economic Resilience
One of the most profound financial literacy lessons from the recent economic turmoil was the vulnerability associated with relying on a single source of income. When industries shut down or companies downsized, those with only one job or highly specialized skills in a declining sector faced immediate and severe financial hardship. This led many to consider or actively pursue alternative income streams, side hustles, or upskilling opportunities.
The rise of the gig economy, remote work, and online entrepreneurship accelerated during this time, as people sought ways to supplement lost income or create new avenues for revenue. This wasn’t just about survival; it was also about building resilience. Having multiple income streams acts as a personal diversification strategy, much like diversifying an investment portfolio. If one source dries up, others can help cushion the blow.
Moreover, the crisis highlighted the importance of continuous learning and skill development. Those who could adapt their skills to new demands or acquire new, in-demand competencies found themselves in a stronger position in the job market. This proactive approach to career and income generation is a critical aspect of modern financial literacy lessons. It encourages individuals to think beyond their current job and consider how they can leverage their talents, time, and resources to create multiple avenues for financial stability. This long-term perspective on income generation is a powerful tool for navigating an increasingly dynamic and unpredictable global economy.
5. The Psychological Aspect of Money: Patience, Panic, and Planning
Beyond the practicalities of budgeting and saving, the recent economic stimulus measures and the accompanying uncertainty offered a stark reminder of the psychological dimensions of money management. Fear, anxiety, and even panic can lead to irrational financial decisions, such as selling investments at a loss during a market downturn or making impulsive purchases when stimulus checks arrive. Conversely, a sense of relief can lead to complacency, causing individuals to neglect crucial financial planning once the immediate crisis passes.
A significant financial literacy lesson here is the importance of emotional intelligence in financial decision-making. Developing patience, resisting the urge to panic during market volatility, and sticking to a well-thought-out financial plan are invaluable skills. The stimulus measures, while beneficial, also created a complex psychological environment. For some, the checks felt like ‘free money,’ leading to spending that didn’t align with long-term financial goals. For others, the fear of future uncertainty led to hoarding cash rather than strategically investing or paying down high-interest debt.
This period emphasized that true financial literacy isn’t just about understanding numbers; it’s also about understanding oneself. It involves developing the discipline to adhere to a budget, the foresight to plan for future contingencies, and the emotional fortitude to navigate economic ups and downs without succumbing to fear or greed. Engaging in financial education, seeking advice from trusted professionals, and consciously practicing delayed gratification are all part of cultivating this crucial psychological resilience. This holistic approach to money management, integrating both practical strategies and emotional awareness, solidifies the comprehensive nature of effective financial literacy lessons.
Beyond the CARES Act: Applying Financial Literacy Lessons for the Future
The CARES Act and subsequent economic stimulus packages were extraordinary responses to an extraordinary crisis. While they provided critical relief, their true lasting value lies in the profound financial literacy lessons they offered. These experiences served as a stress test for personal finance, revealing vulnerabilities and highlighting the strengths of sound financial practices. It’s not enough to simply have received aid; the real benefit comes from internalizing these lessons and integrating them into our ongoing financial habits.
Building Sustainable Financial Habits
The journey towards robust financial health is continuous. It requires consistent effort and a willingness to adapt. The first step is to honestly assess your current financial situation in light of these lessons. Do you have an adequate emergency fund? Is your debt manageable? Do you understand where your money is going each month? Answering these questions truthfully is the foundation for building sustainable habits.
- Automate Savings: Make saving for your emergency fund and other goals automatic. Set up recurring transfers from your checking to your savings account immediately after you get paid. This ‘pay yourself first’ strategy is incredibly effective.
- Regularly Review Your Budget: Life circumstances change, and so should your budget. Make it a habit to review your income and expenses monthly or quarterly, adjusting as needed. This ensures your budget remains a relevant and useful tool.
- Prioritize Debt Repayment: Focus on eliminating high-interest debt. Consider strategies like the debt snowball or debt avalanche method to gain momentum and reduce interest payments over time.
- Invest in Yourself: Continuously seek opportunities to learn new skills or enhance existing ones. This not only boosts your career prospects but also increases your earning potential and financial resilience.
- Educate Yourself: Stay informed about economic trends, personal finance strategies, and investment opportunities. Read reputable financial publications, listen to podcasts, and consider taking online courses.
The Role of Financial Planning
Effective financial planning goes beyond day-to-day money management. It involves setting long-term goals, such as retirement planning, buying a home, or funding education, and creating a roadmap to achieve them. The volatility of the past few years underscored that even the best-laid plans can be disrupted, making flexibility and contingency planning crucial.
Working with a qualified financial advisor can be immensely beneficial, especially for navigating complex financial decisions and developing a comprehensive plan tailored to your specific situation. They can help you understand investment options, optimize your retirement savings, and develop strategies for wealth preservation and growth. This professional guidance can be a powerful accelerator in applying financial literacy lessons effectively.
Cultivating a Mindset of Resilience
Perhaps one of the most subtle yet powerful financial literacy lessons is the cultivation of a resilient mindset. Economic cycles are inevitable, and crises will occur again. What distinguishes those who navigate these challenges successfully is not necessarily their income level, but their preparedness and their approach. A resilient mindset involves:
- Optimism with Realism: Believing in your ability to overcome financial challenges while realistically assessing risks.
- Adaptability: Being willing to adjust your plans and strategies when circumstances change.
- Patience: Understanding that financial success is a marathon, not a sprint, and that consistent, disciplined effort yields results over time.
- Continuous Learning: Viewing every economic event, positive or negative, as an opportunity to learn and refine your financial understanding.
Conclusion: Empowering Your Financial Future with Key Financial Literacy Lessons
The CARES Act and subsequent government stimulus initiatives were more than just financial aid; they were a profound, collective experience that illuminated critical aspects of personal finance. The five financial literacy lessons we’ve explored – the imperative of an emergency fund, strategic debt management, diligent budgeting, diversifying income, and understanding money psychology – are not merely theoretical concepts. They are practical, hard-won insights that, when applied, can fundamentally transform your financial well-being.
By internalizing these lessons and committing to continuous financial education and disciplined action, you can move beyond merely reacting to economic events. Instead, you can proactively build a robust, resilient financial future, capable of weathering storms and seizing opportunities. The time to apply these invaluable financial literacy lessons is now, ensuring that you are not just surviving, but thriving, in an ever-evolving economic world.
Embrace these insights, make them a part of your daily financial regimen, and empower yourself with the knowledge and habits necessary to navigate whatever economic future lies ahead. Your financial independence and peace of mind depend on it.