Small Business Lending in 2026: Accessing Capital and Understanding New Loan Programs in the US
Anúncios
The landscape of small business lending is in a perpetual state of evolution, driven by technological advancements, shifts in economic policy, and the ever-changing needs of entrepreneurs. As we look ahead to 2026, understanding the nuances of small business lending 2026 becomes paramount for any aspiring or existing business owner in the United States. The ability to access capital is often the lifeblood of a small business, enabling growth, innovation, and resilience in a competitive market. This comprehensive guide aims to demystify the future of business financing, offering insights into emerging trends, new loan programs, and strategic approaches to secure the funding your venture needs.
Anúncios
The past few years have accelerated the adoption of digital platforms and alternative lending solutions. Traditional banking institutions are adapting, and new players are constantly entering the market, creating a dynamic and, at times, complex environment for small business owners. Navigating this complexity requires foresight, a clear understanding of your business’s financial health, and an awareness of the diverse funding options available. Our focus here is to provide a forward-looking perspective, equipping you with the knowledge to make informed decisions about small business lending 2026.
The Evolving Landscape of Small Business Lending in 2026
The year 2026 promises a further refinement of the trends we’ve witnessed in recent years within the small business lending 2026 sector. Digital transformation will continue to be a dominant force, with an increasing number of lenders leveraging artificial intelligence (AI) and machine learning (ML) for more efficient underwriting and personalized loan products. This shift means faster application processes, quicker approval times, and potentially more tailored financial solutions for businesses of all sizes, particularly small ones.
Anúncios
One significant aspect of this evolution is the continued growth of non-bank lenders. These entities, often referred to as FinTech lenders, have carved out a substantial niche by offering flexible products and streamlined experiences that traditional banks may struggle to match. Their agility and willingness to embrace new data sources for credit assessment will make them even more prominent in 2026. However, traditional banks are not standing still; many are investing heavily in their own digital capabilities and forming partnerships with FinTech companies to remain competitive in the small business lending 2026 space.
Moreover, economic factors will play a crucial role. Interest rate fluctuations, inflation, and overall economic stability will influence lender appetite and the cost of borrowing. Small businesses must remain vigilant, monitoring these macroeconomic indicators to identify optimal times for seeking capital. Government policies and regulatory changes will also shape the environment, potentially introducing new incentives or restrictions that impact loan availability and terms. Staying informed about these broader economic and regulatory shifts is just as important as understanding the specific loan products available.
Key Trends Shaping Small Business Lending in 2026
- Hyper-Personalization of Loan Products: AI and big data analytics will allow lenders to offer highly customized loan products based on a business’s specific industry, cash flow patterns, and growth trajectory. This moves beyond a one-size-fits-all approach to financing.
- Embedded Finance: Expect to see more lending options integrated directly into the platforms small businesses already use, such as accounting software, e-commerce platforms, and payment processors. This seamless integration makes accessing capital more convenient and less disruptive.
- Focus on Cash Flow Lending: Lenders will increasingly prioritize a business’s cash flow over traditional collateral, especially for service-based businesses or those with limited tangible assets. This approach provides more opportunities for growth-oriented businesses.
- Sustainability and ESG-Linked Loans: As environmental, social, and governance (ESG) factors become more critical, expect to see an increase in loan programs that offer preferential terms to businesses demonstrating strong sustainability practices or contributing positively to their communities.
- Increased Transparency and Disclosure: Regulatory bodies may push for greater transparency in lending terms, fees, and repayment structures, especially from online and alternative lenders, aiming to protect small business borrowers.
New and Emerging Loan Programs for Small Businesses in 2026
Beyond the existing staples like SBA loans and traditional bank lines of credit, 2026 is expected to bring a host of new and refined loan programs designed to meet the diverse needs of small businesses. These programs often target specific sectors, business stages, or demographic groups, reflecting a more nuanced understanding of the small business ecosystem.
Government-Backed Initiatives and SBA Enhancements
The Small Business Administration (SBA) will continue to be a cornerstone of small business lending 2026. While the core 7(a), 504, and Microloan programs will remain, expect to see further adjustments and potential new pilot programs. These could include:
- Streamlined SBA Express Loans: Further simplification of the application process for SBA Express loans, making it even faster for small businesses to access smaller amounts of capital.
- Sector-Specific Grants and Loans: Potential for new government programs targeting critical sectors like renewable energy, advanced manufacturing, or healthcare innovation, offering specialized funding or subsidies.
- Enhanced Disaster Relief Funding: Continued refinement of disaster loan programs to provide quicker and more efficient support to businesses affected by natural disasters, with a focus on long-term recovery.
It’s crucial for businesses to regularly check the SBA website and consult with SBA-approved lenders to stay updated on these evolving programs. The SBA plays a vital role in de-risking loans for lenders, which in turn makes capital more accessible and affordable for small businesses.
FinTech-Driven Innovative Loan Products
FinTech lenders are at the forefront of innovation in small business lending 2026. Their ability to leverage technology allows them to create agile and often unconventional financing solutions. Some of the emerging products to watch for include:
- Revenue-Based Financing (RBF) 2.0: An evolution of RBF where repayment is directly tied to a percentage of future revenue, but with more sophisticated algorithms that adjust payment schedules based on real-time business performance, offering greater flexibility during lean months.
- Embedded Working Capital Solutions: As mentioned, these will become more prevalent, offering instant access to funds directly within platforms like Shopify, Square, or QuickBooks, based on transactional data.
- Invoice Factoring and Supply Chain Finance with AI: AI will enhance the efficiency and accessibility of invoice factoring and supply chain finance, allowing businesses to unlock capital from their outstanding invoices or optimize their supply chain financing with greater ease and lower costs.
- Tokenized Asset-Backed Loans: While still nascent, the concept of using tokenized real-world assets (e.g., intellectual property, future royalties) as collateral for loans could gain traction, especially for innovative startups.
These innovative products often come with different eligibility criteria and repayment structures than traditional loans, so understanding their mechanics is key.
Community Development Financial Institutions (CDFIs) and Micro-Lenders
CDFIs and micro-lenders will continue to play a critical role in providing capital to underserved communities and businesses that may not qualify for traditional bank loans. These institutions often offer:
- Tailored Technical Assistance: Beyond just capital, CDFIs often provide invaluable business coaching, financial literacy training, and mentorship, which are crucial for the success of nascent businesses.
- Flexible Underwriting: They are often more willing to consider factors beyond traditional credit scores, such as character, community impact, and non-traditional collateral.
- Targeted Programs: Many CDFIs have specific programs for women-owned businesses, minority-owned businesses, veterans, or businesses in low-income areas, reflecting a commitment to equitable access to capital.
For small businesses struggling to secure funding through conventional channels, exploring CDFIs and micro-lenders can be a highly effective strategy in small business lending 2026.
Accessing Capital in 2026: Strategies for Small Business Owners
Securing capital in 2026 will require a proactive and strategic approach. It’s no longer enough to simply fill out an application; businesses need to present a compelling case, understand their financial health deeply, and know where to look for the right type of funding.
1. Optimize Your Financial Health and Credit Profile
Lenders, regardless of their type, will always scrutinize your business’s financial stability. In 2026, with advanced analytics, this scrutiny will be even more precise. Key areas to focus on include:
- Strong Credit Score (Personal and Business): Maintain excellent personal credit, as it often impacts small business loan eligibility. Build and monitor your business credit score by paying vendors on time and establishing credit accounts under your EIN.
- Robust Cash Flow Management: Demonstrate consistent and positive cash flow. Lenders want to see that your business can generate enough revenue to comfortably cover loan repayments. Implement efficient invoicing and collection practices.
- Clear Financial Statements: Keep accurate and up-to-date financial records, including profit and loss statements, balance sheets, and cash flow statements. These documents are your business’s financial story.
- Manage Debt-to-Income Ratio: A high debt-to-income ratio can signal risk to lenders. Strive to keep your existing debt manageable relative to your income.
Investing in good accounting software and potentially a financial advisor can significantly help in optimizing these aspects of your business’s financial health, making you a more attractive borrower in the realm of small business lending 2026.
2. Develop a Comprehensive Business Plan
Even for established businesses, a well-articulated business plan is crucial when seeking new funding. In 2026, this plan should be dynamic and forward-looking, addressing market trends, competitive advantages, and realistic financial projections.
- Executive Summary: A concise overview of your business, its mission, and its funding needs.
- Company Description: Detail your business structure, products/services, and unique value proposition.
- Market Analysis: Demonstrate a deep understanding of your target market, industry trends, and competitive landscape.
- Organization and Management: Highlight the experience and expertise of your leadership team.
- Service or Product Line: Describe what you offer and its lifecycle.
- Marketing and Sales Strategy: Outline how you plan to reach customers and generate revenue.
- Funding Request: Clearly state how much capital you need, how it will be used, and how it will contribute to growth and repayment.
- Financial Projections: Provide realistic forecasts for revenue, expenses, and profitability, typically for the next 3-5 years.
A strong business plan not only impresses lenders but also serves as a strategic roadmap for your own business operations, a cornerstone of successful small business lending 2026.
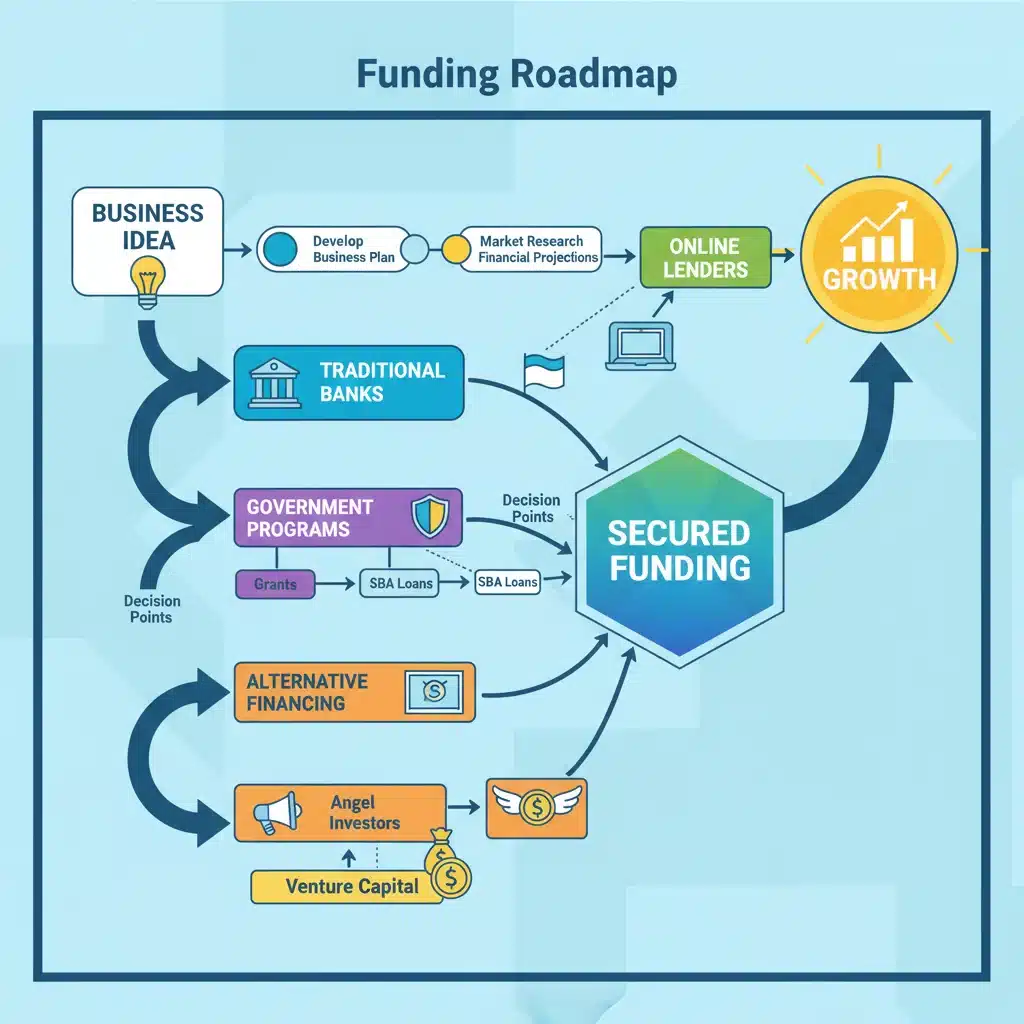
3. Explore Diverse Funding Avenues
Don’t limit yourself to a single type of lender. The diverse ecosystem of small business lending 2026 means there are multiple doors to knock on. Consider:
- Traditional Banks: For established businesses with strong credit and collateral, traditional banks still offer competitive rates and terms, especially for larger loans.
- Online Lenders: Ideal for businesses needing quick access to capital, those with less-than-perfect credit, or those seeking smaller, short-term loans. Be mindful of interest rates and fees.
- SBA-Approved Lenders: Essential for accessing government-backed loans with favorable terms. These can be banks, credit unions, or non-profit lenders.
- Community Development Financial Institutions (CDFIs): Excellent for businesses in underserved areas or those seeking additional support services.
- Venture Capital and Angel Investors: For high-growth potential startups seeking significant equity investment, rather than debt.
- Crowdfunding: Both reward-based and equity crowdfunding can be viable options, especially for innovative products or services with a strong community appeal.
The best approach often involves a combination of these, carefully selected to match your business’s stage, needs, and risk profile.
Understanding the Application Process and Key Considerations
Regardless of the lender or loan type, the application process for small business lending 2026 will typically involve several common steps and considerations. Being prepared can significantly expedite the process and improve your chances of approval.
Required Documentation
While specific requirements vary, commonly requested documents include:
- Personal and Business Financial Statements: Tax returns (personal and business), bank statements, balance sheets, profit and loss statements.
- Business Legal Documents: Business registration, articles of incorporation/organization, licenses, permits.
- Business Plan: As detailed above, outlining your strategy and financial projections.
- Personal Identification: Driver’s license, passport, social security number.
- Collateral Information: If applicable, documentation of assets being pledged (e.g., real estate, equipment, accounts receivable).
- Business Debt Schedule: A list of all existing business debts, including creditors, balances, and payment terms.
Having these documents organized and readily accessible will save valuable time during the application phase.
Key Factors Lenders Evaluate
Lenders typically assess several critical factors, often referred to as the ‘5 Cs of Credit’:
- Character: Your personal and business credit history, reputation, and willingness to repay.
- Capacity: Your business’s ability to repay the loan, assessed through cash flow, revenue, and debt-to-income ratios.
- Capital: Your personal investment in the business, demonstrating your commitment and reducing lender risk.
- Collateral: Assets that can be pledged to secure the loan, providing the lender with recourse if you default.
- Conditions: The economic environment, industry trends, and the purpose of the loan, all of which can influence repayment ability.
Understanding how lenders evaluate these factors allows you to proactively strengthen your business’s position for small business lending 2026.
Navigating Interest Rates and Fees
Interest rates and fees can significantly impact the total cost of a loan. Always compare the Annual Percentage Rate (APR), which includes all fees and interest, to get a true picture of the loan’s cost. Be aware of:
- Origination Fees: A fee charged by the lender for processing the loan.
- Closing Costs: Various fees associated with finalizing the loan, especially for larger, secured loans.
- Prepayment Penalties: Some loans may charge a penalty if you repay the loan early.
- Late Payment Fees: Penalties for missed or late payments.
- Hidden Fees: Always read the fine print and ask for a complete breakdown of all costs associated with the loan.
Transparency in lending is improving, but due diligence remains essential when comparing offers for small business lending 2026.
The Role of Technology and Data in Small Business Lending 2026
Technology is not just changing how loans are processed; it’s fundamentally reshaping who gets access to capital and on what terms. In 2026, the integration of advanced data analytics and AI will be even more pervasive, offering both opportunities and challenges for small businesses.
AI and Machine Learning for Underwriting
AI-powered algorithms can analyze vast amounts of data points in real-time, far beyond what human underwriters can process. This includes:
- Alternative Data Sources: Beyond traditional credit scores, AI can assess social media presence, website traffic, online reviews, payment processing data, and even utility payment history to create a more holistic credit profile.
- Predictive Analytics: AI can predict future cash flow and business performance with greater accuracy, allowing lenders to make more informed decisions and offer more flexible repayment schedules.
- Fraud Detection: Advanced AI models can identify fraudulent applications more effectively, reducing risk for lenders and potentially lowering overall borrowing costs.
For small businesses, this means that even if you have a limited traditional credit history, your operational data could open doors to financing. However, it also means that your digital footprint and operational efficiency will become increasingly important in the small business lending 2026 assessment.
Blockchain and Smart Contracts
While still in early stages for mainstream small business lending, blockchain technology holds significant promise for 2026 and beyond. It can offer:
- Enhanced Security and Transparency: Immutable records of transactions and loan agreements can reduce fraud and increase trust.
- Faster Transactions: Smart contracts can automate loan disbursements and repayments based on predefined conditions, speeding up the entire lending cycle.
- Lower Costs: By eliminating intermediaries and manual processes, blockchain could potentially reduce the administrative costs associated with lending, translating to lower fees for borrowers.
Keep an eye on pilot programs and niche lenders exploring these technologies, as they could eventually become a standard part of small business lending 2026.
Cybersecurity and Data Privacy
As more business data is shared digitally for loan applications, cybersecurity and data privacy become paramount. Small businesses must ensure that their own data security practices are robust and that they are only sharing information with reputable and secure lending platforms. Lenders, in turn, will be under increasing pressure to protect sensitive financial information from breaches.
Preparing Your Small Business for 2026’s Lending Environment
To successfully navigate the small business lending 2026 landscape, proactive preparation is key. Here’s a checklist to ensure your business is ready:
- Embrace Digitalization: Adopt digital accounting software, payment processing systems, and cloud-based tools to streamline your operations and generate clean, accessible data for lenders.
- Regularly Review Financial Health: Don’t wait until you need a loan. Conduct monthly or quarterly financial reviews to identify strengths and weaknesses.
- Build and Maintain Relationships: Foster strong relationships with your bank, even if you primarily use online lenders. A trusted banking partner can offer invaluable advice and support.
- Understand Your Industry: Stay informed about economic forecasts and trends specific to your industry, as these will influence lender confidence.
- Seek Professional Advice: Consult with financial advisors, accountants, or business consultants who specialize in small business financing. Their expertise can be invaluable.
- Start Early: If you anticipate needing capital in 2026, begin your research and preparation well in advance. The more time you have, the better your options will be.
By taking these steps, your small business will be well-positioned to take advantage of the opportunities presented by the evolving small business lending 2026 environment.
Conclusion: Thriving in the Future of Small Business Lending
The future of small business lending 2026 in the US is characterized by innovation, diversification, and an increasing reliance on technology. While traditional lending avenues will persist, the rise of FinTech, specialized government programs, and community-focused lenders will offer a broader spectrum of choices for entrepreneurs. Success in securing capital will hinge on a business’s financial preparedness, a clear understanding of its funding needs, and a strategic approach to exploring the various lending options available.
For small business owners, this means embracing digital tools, maintaining impeccable financial records, and continuously educating themselves on new loan products and market trends. The ability to adapt and leverage technology will not only streamline the borrowing process but also open doors to more flexible and tailored financial solutions. As the economy continues to evolve, access to appropriate capital will remain a critical differentiator for businesses aiming for sustainable growth and long-term success. By staying informed and proactive, small businesses can confidently navigate the lending landscape of 2026 and beyond, securing the funding necessary to turn their visions into reality.